Click to find
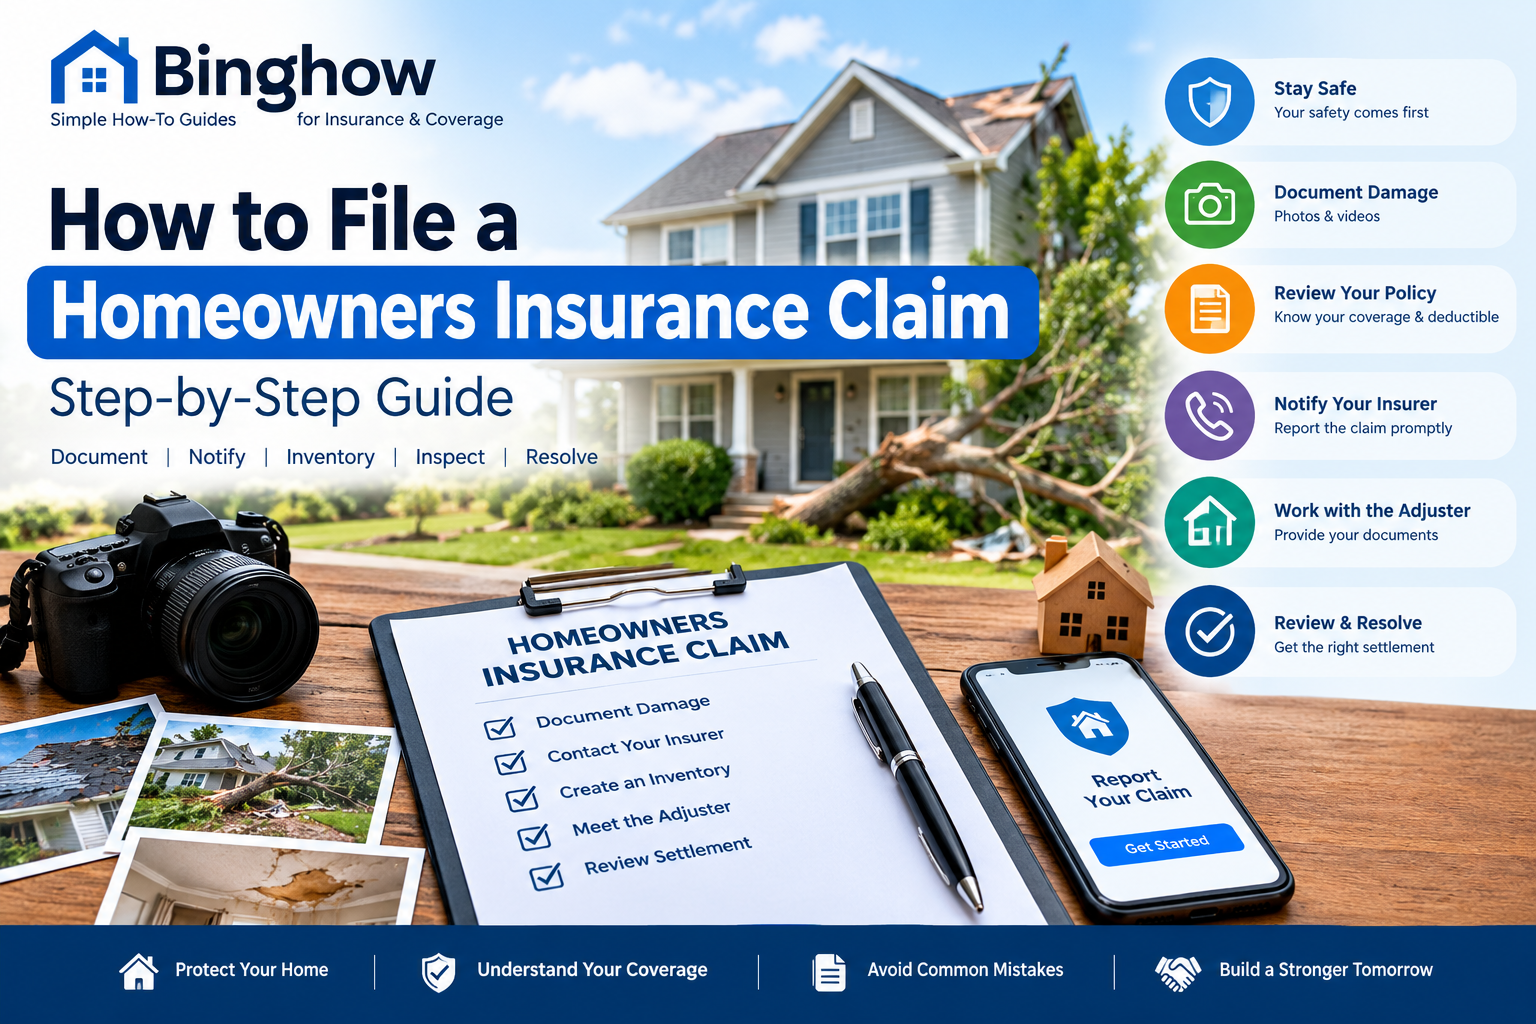
How to File a Homeowners Insurance Claim
If your home has been damaged by a storm, fire, theft, burst pipe, fallen tree, or another covered event, you may need to file a homeowners insurance claim.
The process can feel overwhelming, especially when you are dealing with property damage and unexpected expenses. The good news is that you can make the process easier by following a few organized steps.
To file a homeowners insurance claim, generally you should:
- Make sure everyone is safe.
- Prevent additional damage when reasonably possible.
- Document the damage with photos and videos.
- Review your homeowners insurance policy and deductible.
- Notify your insurance company or agent promptly.
- Prepare an inventory of damaged or lost property.
- Keep receipts and records of temporary repairs and expenses.
- Meet with the insurance adjuster.
- Review the claim estimate and settlement.
- Follow up if the claim is delayed, denied, or appears incomplete.
The exact requirements and deadlines can vary by policy and state, so your policy and state insurance department are important sources of information. The National Association of Insurance Commissioners (NAIC) recommends contacting your insurer as soon as possible after deciding to file a claim.
What Is a Homeowners Insurance Claim?
A homeowners insurance claim is a formal request to your insurance company for payment or coverage after a covered loss damages your home or belongings.
Depending on your policy, coverage may apply to areas such as:
- The structure of your home
- Personal belongings
- Detached structures
- Certain temporary living expenses
- Personal liability
- Certain additional expenses after a covered loss
However, not every type of damage is automatically covered.
For example, standard homeowners insurance generally does not automatically provide flood or earthquake coverage. Separate coverage may be available for certain risks.
That’s why checking your policy before assuming something is covered is important.
How to File a Homeowners Insurance Claim: 10 Steps
1. Make Sure Everyone Is Safe
Your first priority after property damage should be safety.
If there is a fire, gas leak, electrical danger, major structural damage, or another immediate hazard, leave the property and contact the appropriate emergency services.
Do not put yourself at risk simply to photograph damage or recover belongings.
Once the immediate danger has passed, you can begin documenting the loss and contacting your insurer.
2. Prevent Further Damage
After a covered loss, take reasonable steps to prevent the damage from getting worse.
For example, depending on the situation, you might:
- Cover a damaged roof temporarily
- Board up a broken window
- Shut off the water after a major plumbing leak
- Move undamaged belongings away from leaking water
- Arrange temporary protection for exposed areas
NAIC guidance emphasizes documenting the damage before cleanup when possible and taking reasonable mitigation steps afterward to prevent additional destruction. Keep receipts for reasonable emergency expenses and temporary repairs.
Important
Do not make major permanent repairs before your insurance company has had an opportunity to inspect the damage unless immediate action is necessary for safety or to prevent further damage.
Keep damaged materials or items when practical and safe, because your insurer may want to inspect them.
3. Photograph and Video the Damage
Before cleaning up, take detailed photographs and videos.
Capture:
- Wide shots of each affected room
- Close-ups of damaged areas
- Damaged walls and ceilings
- Roof damage
- Broken windows and doors
- Water damage
- Damaged furniture
- Electronics
- Appliances
- Clothing
- Other personal belongings
Try to photograph the same area from multiple angles.
Also photograph the surrounding area if it helps explain what happened.
Why Is Documentation Important?
Photos and videos can help establish the condition of the property after the loss and provide supporting evidence for your claim.
NAIC specifically recommends taking photographs and videos and creating a list of damaged property when filing a homeowners claim.
4. Review Your Homeowners Insurance Policy
Before filing your claim, review your policy if you can.
Look for information about:
- Coverage limits
- Deductible
- Covered causes of loss
- Exclusions
- Personal property coverage
- Additional living expenses
- Replacement cost coverage
- Actual cash value coverage
- Claim reporting requirements
- Duties after a loss
Your deductible is particularly important.
For example, suppose your covered damage is estimated at $15,000 and your deductible is $2,500.
A simplified example would be:
$15,000 covered loss − $2,500 deductible = $12,500
The actual settlement can be different depending on your policy, coverage limits, depreciation, exclusions, and the insurer’s claim determination.
5. Determine Whether Filing a Claim Makes Sense
Not every small repair necessarily requires an insurance claim.
Suppose a minor repair costs approximately $1,000 while your deductible is $2,500. Depending on the circumstances, filing a claim may not result in an insurance payment.
But if the damage is substantial, the cost could be significantly higher than your deductible.
NAIC recommends understanding your deductible and considering the size of the loss before reporting a claim. It also notes that claims can be reported to nationwide claims databases used by insurers.
Important: Don’t delay reporting a potentially significant covered loss simply because you are uncertain. Your policy may have reporting requirements or deadlines.
6. Contact Your Insurance Company
Once you’ve decided to file, contact your insurance company or insurance agent.
Many insurers allow claims to be reported through:
- Phone
- Website
- Mobile app
- Insurance agent
- Emergency claims hotline
Have important information available, such as:
- Policy number
- Your name
- Property address
- Date of loss
- Approximate time of loss
- Description of what happened
- Description of the damage
- Photos and videos
- Emergency repair receipts
NAIC recommends notifying the insurance company as soon as possible after deciding to file a claim. Reporting requirements can vary by state and policy.
7. Create a Detailed Home Inventory
A home inventory can make a homeowners insurance claim much easier to document.
Create a list of damaged or destroyed items.
For each item, record information such as:
| Information | Example |
|---|---|
| Item | Television |
| Brand | Samsung |
| Model | Example model |
| Purchase date | 2024 |
| Approximate price | $900 |
| Condition | Damaged |
| Proof | Receipt/photo |
| Location | Living room |
For expensive belongings, include receipts, photographs, serial numbers, warranties, or other available documentation.
If you did not create an inventory before the loss, don’t assume you cannot document your belongings now. Go room by room and reconstruct the list using photographs, receipts, emails, retailer records, bank statements, or other available evidence.
NAIC recommends maintaining a home inventory and updating it when you purchase new items.
8. Keep Every Receipt and Expense Record
Save documentation for expenses related to the covered loss.
Depending on your policy, potentially relevant records may include:
- Emergency repairs
- Temporary lodging
- Storage
- Cleanup
- Replacement items
- Contractor estimates
- Professional services
Whether an expense is reimbursable depends on the policy and circumstances.
Create a dedicated folder for:
Home Insurance Claim – [Date]
Then save:
- Emails
- Photos
- Videos
- Receipts
- Estimates
- Letters
- Claim numbers
- Adjuster communications
- Contractor documents
Keeping everything organized can make it easier to track your claim.
9. Meet With the Insurance Adjuster
After you report the claim, your insurance company may assign an adjuster to inspect the damage.
The adjuster may:
- Inspect the property
- Photograph damage
- Review your documentation
- Examine damaged items
- Review repair estimates
- Evaluate applicable policy coverage
- Prepare or review a damage estimate
NAIC explains that an insurer’s adjuster evaluates damage and considers the policy, deductibles, and coverage limits when determining the claim amount.
What Should You Give the Adjuster?
Prepare:
- Damage photos
- Videos
- Home inventory
- Receipts
- Contractor estimates
- Repair invoices
- Temporary living expense records
- Relevant correspondence
Be factual and accurate when explaining what happened.
10. Review the Claim Settlement Carefully
Once your insurer evaluates the claim, review the settlement information carefully.
Look at:
- Damage included
- Damage excluded
- Deductible
- Depreciation
- Coverage limits
- Repair estimates
- Personal property valuation
- Additional living expenses
- Any unexplained differences
One important distinction is Actual Cash Value (ACV) versus Replacement Cost Value (RCV).
With ACV, depreciation can reduce the amount paid for damaged property.
With replacement cost coverage, the policy may provide payment based on the cost of replacing or repairing covered property, subject to policy terms and limits.
Actual Cash Value vs. Replacement Cost
Understanding this difference can prevent confusion about your homeowners insurance settlement.
Actual Cash Value
ACV generally considers depreciation based on the age and condition of the property.
For example:
A five-year-old television may cost $1,000 to replace today, but its depreciated value may be lower.
Replacement Cost
Replacement cost coverage generally focuses on the cost to repair or replace covered property with materials of like kind and quality, subject to the policy.
The exact calculation depends on your policy.
Don’t assume that the home’s market value is the same thing as its replacement cost. NAIC distinguishes replacement cost from market value because market value includes factors such as land and real-estate-market conditions.
What Does Homeowners Insurance Usually Cover?
Coverage depends on the specific policy, but homeowners policies can include protection for areas such as:
Dwelling
The physical structure of the home, including certain built-in components.
Other Structures
Depending on the policy, this can include structures such as:
- Detached garages
- Sheds
- Fences
Personal Property
This may include belongings such as:
- Furniture
- Clothing
- Electronics
- Appliances
- Certain valuables
Loss of Use / Additional Living Expenses
If a covered loss makes the home temporarily uninhabitable, your policy may provide coverage for certain additional living expenses.
Liability
Homeowners policies may also provide personal liability coverage for certain covered accidents involving injury or property damage.
NAIC identifies dwelling, other structures, personal property, loss of use, and liability as important components of homeowners insurance, while noting that coverage varies by policy.
What Is Usually Not Covered by Standard Homeowners Insurance?
A homeowners policy does not cover every possible cause of property damage.
Common examples that may require separate coverage or may be excluded include:
- Flood damage
- Earthquake damage
- Certain maintenance problems
- Normal wear and tear
- Certain types of water damage
- Intentional damage
The exact exclusions depend on the policy.
For example, flood insurance is generally separate from standard homeowners insurance.
Always check the actual policy rather than relying on a general list of exclusions.
How Long Do You Have to File a Homeowners Insurance Claim?
There is no single nationwide deadline that applies to every homeowners insurance claim.
Your policy and state law may establish requirements for reporting losses.
Some policies require prompt notice or specify a particular timeframe.
That’s why contacting your insurer as soon as reasonably possible is generally a good practice after a significant loss. NAIC states that reporting requirements vary by state and recommends notifying the insurer promptly.
What If Your Homeowners Insurance Claim Is Denied?
A denied claim does not necessarily mean the process ends there.
First, read the denial letter carefully.
Look for:
- The reason for denial
- Policy language cited by the insurer
- Exclusions
- Coverage limits
- Missing documentation
- Disputed cause of damage
Then gather your supporting documents.
You may want to:
- Ask the insurer for an explanation.
- Request clarification of the policy language.
- Provide additional documentation if appropriate.
- Ask whether the decision can be reconsidered.
- Contact your state’s insurance department if you believe the insurer has not handled the claim properly.
- Consider professional legal or claims assistance when appropriate.
State insurance departments can investigate certain consumer complaints involving issues such as claim delays, denials, failure to honor policies, or possible violations of state insurance laws.
What If Your Insurance Claim Is Underpaid?
If the settlement appears lower than the amount necessary to repair covered damage, start by comparing the insurer’s estimate with your contractor’s estimate.
Check whether:
- Every damaged area was included
- The correct materials were listed
- Labor costs were included
- Depreciation was applied
- Your deductible was correctly applied
- Coverage limits were considered
- Certain items were excluded
Ask your insurer to explain differences you don’t understand.
Keep written records of your communications.
For a significant dispute, you may also want to consult an appropriately licensed insurance professional or attorney familiar with property insurance claims in your state.
Common Homeowners Insurance Claim Mistakes
Avoid these common mistakes when filing a home insurance claim.
1. Waiting Too Long
Delaying notification can create problems if your policy has reporting requirements.
2. Failing to Document Damage
Take photos and videos before cleanup whenever reasonably possible.
3. Throwing Away Damaged Property Too Quickly
If practical and safe, preserve damaged items until your insurer has had an opportunity to inspect them.
4. Starting Major Repairs Before Inspection
Emergency mitigation may be necessary, but major permanent repairs should generally be coordinated with your insurer when possible.
5. Losing Receipts
Keep receipts for repairs and other expenses connected with the loss.
6. Guessing About What Happened
Give your insurer accurate information. Don’t exaggerate the damage or speculate about facts you don’t know.
7. Accepting an Estimate You Don’t Understand
Ask questions if the settlement or estimate doesn’t make sense.
8. Not Reading the Policy
Your policy is the key document that defines your coverage, exclusions, limits, and obligations.
Homeowners Insurance Claim Checklist
Before submitting your claim, use this quick checklist:
Before Filing
- Make sure everyone is safe
- Prevent additional damage
- Photograph the damage
- Record video
- Review your policy
- Check your deductible
- Identify potentially covered damage
When Filing
- Contact your insurer
- Provide your policy number
- Explain what happened
- Provide photographs
- Create a damage inventory
- Save the claim number
- Ask about required documents
During the Claim
- Meet with the adjuster
- Keep receipts
- Keep contractor estimates
- Save emails and letters
- Record phone calls and important conversations
- Review the settlement carefully
Frequently Asked Questions
How do I file a homeowners insurance claim?
Contact your insurance company or agent as soon as possible, provide your policy information and details about the loss, document the damage with photos and videos, create an inventory of damaged property, and provide supporting documents requested by the insurer.
Should I file a homeowners insurance claim for a small repair?
It depends on the size of the loss, your deductible, your policy, and your circumstances. If the repair cost is below or only slightly above your deductible, you may want to understand the financial implications before filing.
How long does a homeowners insurance claim take?
There is no universal timeframe. Simple claims may move relatively quickly, while major losses involving extensive property damage, multiple contractors, or coverage disputes can take much longer.
Can I file a homeowners insurance claim without receipts?
Yes, you can still document your belongings and losses if you don’t have every receipt. Photographs, purchase records, bank statements, emails, retailer records, warranties, and other evidence may help establish ownership and value.
What happens after I file a home insurance claim?
The insurer generally reviews the claim, investigates the loss, evaluates the damage, applies the policy’s coverage and deductible provisions, and determines the appropriate payment or coverage position.
What should I do if my homeowners insurance claim is denied?
Read the denial letter, understand the policy language and reason for denial, gather supporting documentation, and ask the insurer for clarification or reconsideration. You can also contact your state’s insurance department about available complaint procedures.
Does homeowners insurance cover flood damage?
Standard homeowners insurance generally does not automatically cover flood damage. Flood insurance is typically separate, so check your policy and applicable coverage.
What is the difference between ACV and replacement cost?
Actual cash value generally accounts for depreciation, while replacement cost coverage generally focuses on the cost to repair or replace covered property, subject to the policy’s terms and limits.
Final Thoughts
Knowing how to file a homeowners insurance claim can make an already stressful situation easier to manage.
The basic process is straightforward:
Document → Notify → Inventory → Inspect → Review → Resolve
Take photographs and videos, protect the property from further damage when reasonably possible, understand your deductible, notify your insurer promptly, and keep detailed records throughout the process.
Most importantly, don’t rely solely on general insurance advice. Your actual homeowners policy and the laws of your state determine what is covered, what you must do after a loss, and what deadlines may apply.
For additional information, homeowners can also consult their state insurance department and consumer resources from the National Association of Insurance Commissioners.